When you’re comparing health insurance plans, the monthly premium is usually the first number that gets your attention. It’s easy to understand, easy to compare, and it tells you what you’ll need to budget each month just to keep your coverage active.
It doesn’t, however, tell you what your healthcare will actually cost.
Deductibles, copays, coinsurance, prescription coverage, provider networks, and out-of-pocket limits can all affect how much you ultimately spend. Two plans with very different premiums could look completely different once you factor in how you actually use your coverage.
That’s why choosing health insurance based on the monthly premium alone can leave you with an incomplete picture. The better approach is to understand how the costs work together, then compare plans based on your healthcare needs and budget.
Your Premium Is Only One Part of the Cost
Your premium is the amount you pay each month to maintain your health insurance coverage, whether you use healthcare services that month or not.
It’s an important number, but it shouldn’t be viewed in isolation.
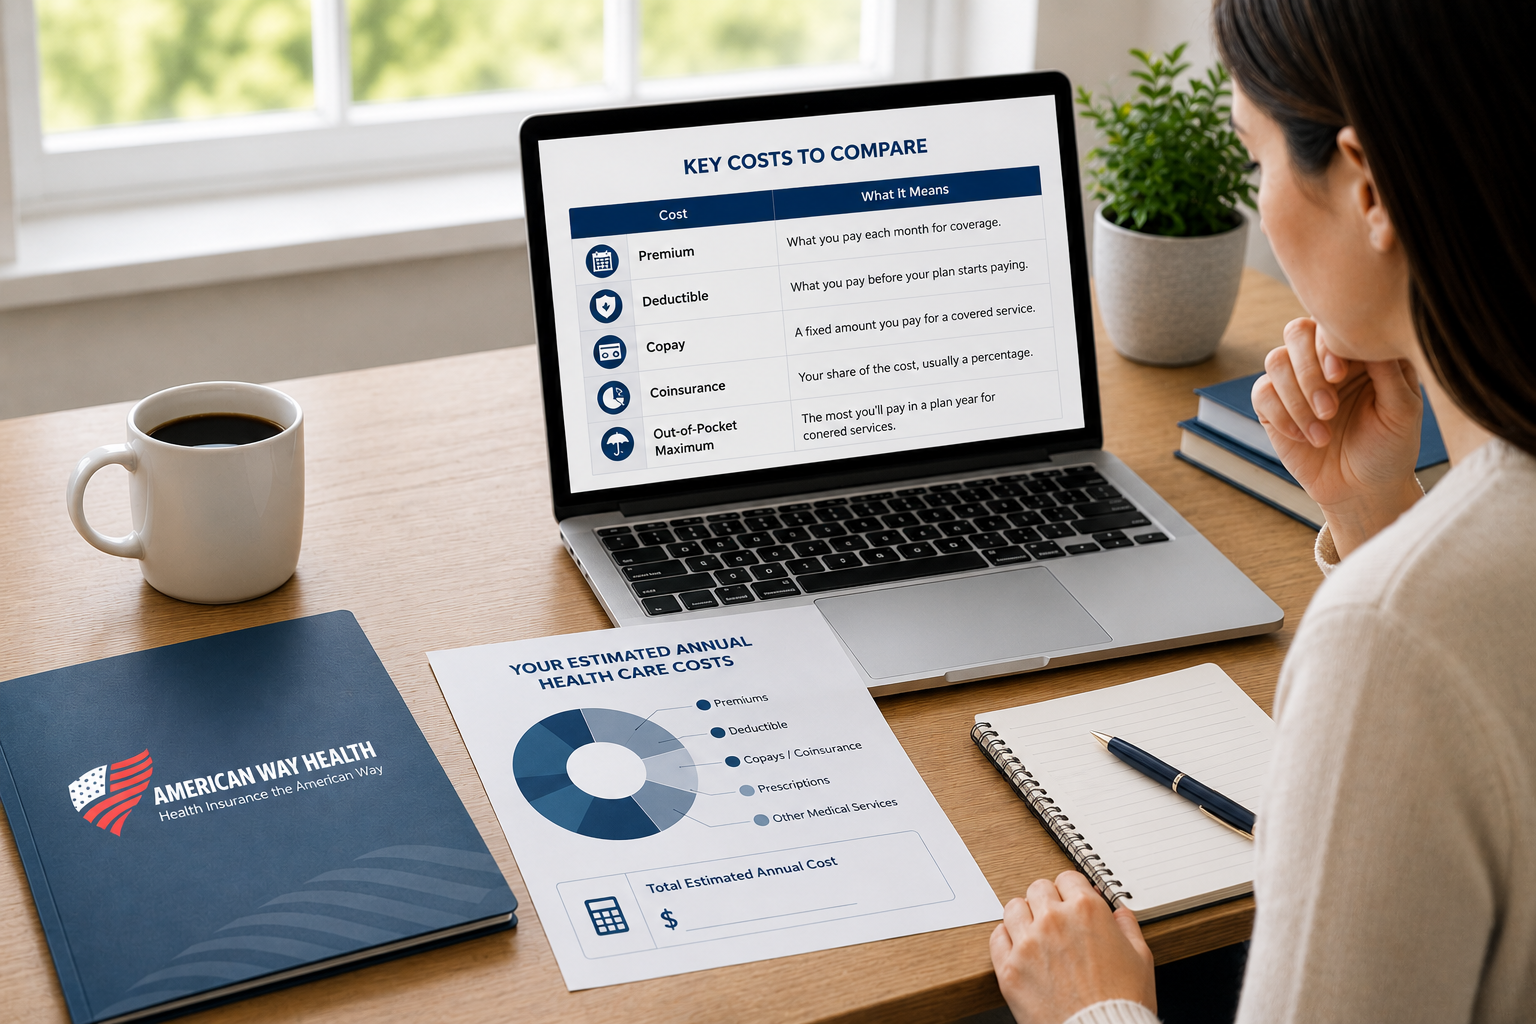
A plan with a lower premium may come with a higher deductible or greater cost sharing when you receive care. Another plan may cost more each month but require you to pay less for certain services throughout the year. HealthCare.gov specifically recommends comparing estimated total yearly costs rather than premiums alone when evaluating Marketplace plans. This is what we do at American Way Health.
Compare your All-In Cost Estimate for the Year:
The important costs to understand include:
- Premium: The amount you pay each month for your coverage.
- Deductible: The amount you may need to pay for certain covered healthcare services before your plan begins paying its share.
- Copay: A fixed amount you may pay when receiving a covered service, such as a doctor’s visit.
- Coinsurance: A percentage of the allowed cost of a covered service that you’re responsible for paying, typically after meeting your deductible.
- Out-of-pocket maximum: The most you’ll pay for covered in-network services that count toward the limit during a plan year. Premiums generally don’t count toward this amount.
None of these numbers tells the entire story by itself. It’s how they work together, combined with the healthcare you expect to use, that gives you a much clearer picture of a plan’s potential cost.
Look at How You Actually Use Healthcare
There isn’t one health insurance plan that’s automatically the most cost-effective for everyone.
Someone who rarely visits a doctor and primarily wants protection against unexpected medical expenses may evaluate their options differently than someone who regularly sees specialists, fills several prescriptions, or anticipates ongoing care.
Before comparing plans, think about what a typical year of healthcare looks like for you and your family.
How often do you visit your primary care provider? Do you regularly see specialists? Are there prescriptions you take every month? Do you expect any planned procedures or ongoing treatment? Are there particular doctors or healthcare facilities you want to continue using?
These questions give context to the numbers you’re comparing.
Provider networks deserve particular attention. Depending on the type of plan, receiving care outside the network may cost more or may generally not be covered except in certain circumstances, such as emergencies.
Prescription benefits can also vary between plans, including which medications are covered and how your share of the cost is structured.
The goal isn’t to predict every healthcare expense you’ll encounter. That’s impossible. It’s to choose coverage with a realistic understanding of how you expect to use it.
Think in Terms of Total Cost, Not the Cheapest Plan
A low premium can be appealing, especially when you’re trying to keep monthly expenses under control. The key is understanding what you’re receiving in exchange for that lower monthly payment.
Consider two hypothetical plans.
One has a lower monthly premium but a relatively high deductible. The other costs more each month but has a lower deductible and different copays or coinsurance.
If you use very little healthcare during the year, the first plan could potentially make sense for your circumstances. If you regularly need medical services, however, the second plan’s higher premium could be offset by how its other costs and benefits apply when you receive care.
This doesn’t mean that a higher-premium plan is inherently better, either. It simply means that price and value aren’t the same thing.
Your out-of-pocket maximum is another number worth considering, particularly when thinking about the financial impact of an unexpectedly high-use year. For 2026 Marketplace plans, the out-of-pocket limit can’t exceed $10,600 for an individual or $21,200 for a family, although individual plans can have lower limits. Those limits don’t include monthly premiums, uncovered services, or certain other expenses.
Instead of asking, “Which plan has the lowest premium?” try asking:
“Which plan gives me the right balance between what I pay each month and what I could pay when I actually need care?”
That question gets much closer to the information you need to make an informed decision.
Compare the Whole Plan Before You Choose
Health insurance has a lot of moving parts, but comparing plans doesn’t need to become an exercise in choosing whichever spreadsheet has the smallest number at the top.
Start with the premium, then keep going.
Look at the deductible and out-of-pocket maximum. Review copays and coinsurance for services you’re likely to use. Check whether your preferred doctors and facilities participate in the network, and review how your prescriptions are covered.
Most importantly, compare those details based on your circumstances rather than someone else’s.
A plan that’s well suited to a healthy individual who rarely needs care may not be the right choice for a family expecting regular appointments and prescriptions. Likewise, paying more each month for benefits you’re unlikely to use may not provide the value you’re looking for.
HealthCare.gov’s guidance follows the same basic principle, recommending that consumers consider the types and amount of healthcare and prescription drugs their household expects to use when estimating total yearly costs.
The best comparison isn’t simply plan against plan. It’s each plan against the healthcare needs, financial priorities, and level of protection that matter to you.
Your Next Step
Understanding the true cost of health insurance gets easier when you can see your options side by side.
American Way Health helps individuals and families compare health insurance plans from a broad range of insurance companies, with licensed advisors who can walk you through premiums, deductibles, networks, benefits, and other important plan details.
Rather than choosing based on one attractive number, you can get a clearer picture of the coverage available and make a decision based on what matters to you.
Ready to see how your options compare? Get your free personalized quote and find health insurance coverage that fits your healthcare needs and budget.